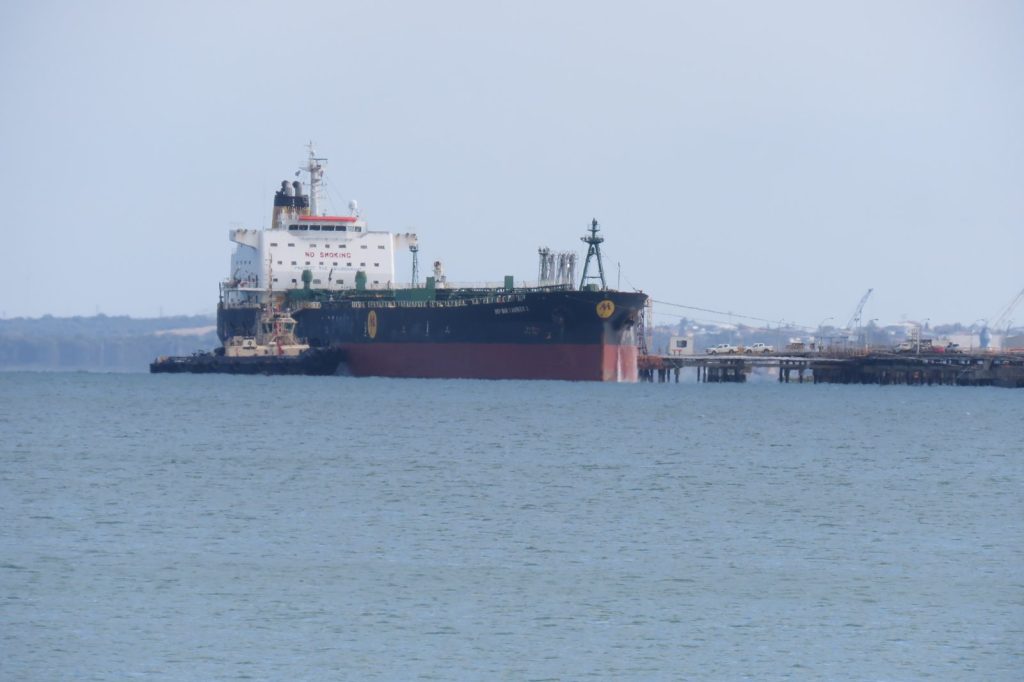
WASHINGTON, July 8 — A 21-mile-wide maritime chokepoint carries roughly one-fifth of the world’s daily oil consumption. That is the Strait of Hormuz, the waterway between Oman and Iran, and the record shows it remains the single most concentrated vulnerability in global energy supply chains. According to the U.S. Energy Information Administration, the strait handles approximately 17 million barrels per day, or about 20 percent of global oil consumption.
Global oil demand in 2024 stood at 102 million barrels per day, meaning the volume transiting Hormuz alone equals the entire daily consumption of several large industrial economies combined. The numbers on the timeline are stark.
Iran’s oil production averaged 3.2 million barrels per day in 2024, with exports of 1.5 million barrels per day. Saudi Arabia produced 9.5 million barrels per day that same year. The United Arab Emirates produced 3.2 million barrels per day.
Together, the three Gulf states that border or dominate access to the strait account for a substantial share of the world’s marginal supply.
The Price Shock Scenario
The EIA has modeled what a closure of the Strait of Hormuz would mean for global markets. The estimate: a price increase of 30 to 50 percent. That is not a theoretical abstraction.
It is a calculation based on the physical volume of oil that would be removed from the market overnight, the lack of ready alternatives, and the time required to reroute tankers or bring spare production online. On the timeline, the U.S. Strategic Petroleum Reserve held 375 million barrels as of March 2025.
That reserve exists precisely for contingencies like a Hormuz closure. But 375 million barrels, while substantial, would cover only about 22 days of the strait’s normal throughput at current consumption rates. OPEC’s spare capacity in 2024 was 5.8 million barrels per day, concentrated primarily in Saudi Arabia and the UAE.
Those two countries are also the ones most dependent on the strait for their own exports. The paradox is that the countries with the most spare capacity are also the ones most directly affected by a closure, since their oil would be trapped behind the same chokepoint.
The Financial Signal
Sources familiar with market movements noted a specific data point from April 4, 2025. On that date, the U.S. dollar index fell 0.3 percent following an announcement by President Trump. Currency markets often move on geopolitical risk, and the dollar’s dip that day signaled investor concern about the stability of Gulf energy flows.
The dollar index decline was modest, but the record shows it occurred in direct response to a presidential statement. For analysts tracking the intersection of energy security and currency markets, the movement was a reminder that the Strait of Hormuz is not merely an oil story.
It is a dollar story. Oil is priced in dollars, and any disruption to the world’s largest oil transit chokepoint reverberates through currency markets, bond yields, and the balance sheets of importing nations. Iran’s position in this equation is central.
The country sits on one side of the strait and has both the geographic proximity and the military capability to threaten shipping. Iran’s 3.2 million barrels per day of production and 1.5 million barrels per day of exports give it a direct stake in the waterway’s operation, but also a potential lever.
Tehran has periodically threatened to close the strait in response to sanctions or military pressure, a threat that has been tested in exercises and diplomatic statements for decades.
The Tanker Calculus
The physical dimensions of the strait compound the risk. At 21 miles wide, the navigable channel for supertankers is narrower still, constrained by shipping lanes, depth requirements, and territorial waters. A single mine, a disabled vessel, or a precision strike could block the channel for days or weeks.
Insurance rates for tankers transiting the strait have historically spiked during periods of tension. The cost of war risk premiums is passed through to oil prices, meaning that even the credible threat of disruption can move markets before any actual incident occurs.
Saudi Arabia and the UAE have invested in pipeline bypasses to reduce their dependence on the strait. The East-West Pipeline in Saudi Arabia can move crude from the kingdom’s eastern fields to the Red Sea, bypassing Hormuz entirely. The UAE operates the Habshan-Fujairah pipeline, which connects its oil fields to the Gulf of Oman.
But these pipelines have limited capacity relative to the volume that normally transits the strait, and they cannot fully replace the water route.
What to Watch Next
On the timeline, the key variables are Iranian export levels, Saudi and UAE spare capacity utilization, and the status of the U.S. Strategic Petroleum Reserve. Any sustained reduction in Hormuz traffic would test the global system’s ability to absorb shock. The 5.8 million barrels per day of OPEC spare capacity is the first line of defense.
But bringing that capacity online takes time — weeks to months — and the quality of the crude may not match the grades that refineries are configured to process. The 375 million barrels in the Strategic Petroleum Reserve provide a second buffer, but releasing that oil is a political decision as much as an operational one.