
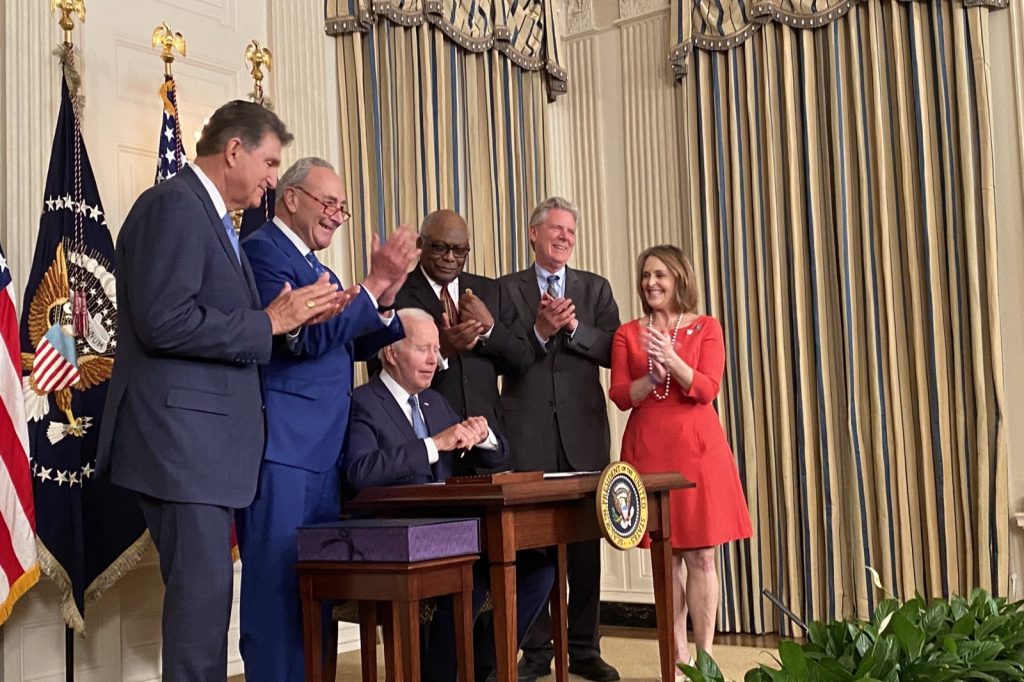
WASHINGTON — The Inflation Reduction Act’s climate and energy package is now in effect, and the mechanics of its tax-credit architecture are coming into sharper focus. The claim was always that these incentives would reshore clean-energy supply chains. The catch, on closer reading of the actual provisions, is that the money flows through a narrow set of channels, and not all of them are equally open.
The core mechanism is a 30% investment tax credit for advanced manufacturing facilities that produce components such as battery cells and solar panels. That is a direct subsidy to build factories on American soil.
On top of that, a separate $3 billion investment in battery manufacturing and recycling was already flowing through the Bipartisan Infrastructure Law of 2021, which predates the IRA but is now operating in tandem with it. Follow the money: the IRA’s climate and energy allocation is approximately $369 billion, but the battery-specific piece was laid out in the earlier law. The European Union is watching this closely, because its own Circular Economy Action Plan, adopted on March 11, 2020, takes a different approach.
Rather than tax credits, Brussels set binding recycling targets: 55% of plastic packaging waste must be recycled by 2030, 65% of municipal waste by 2035, and landfilling separately collected waste is banned outright. The plan also pushes eco-design and reductions in single-use plastics.
The contrast is sharp — the U.S. uses the tax code as a lever; the EU uses mandates and deadlines. Japan, for its part, enacted the Act on Promotion of Resource Circulation for Plastics in June 2022. That law requires plastic product manufacturers to reduce use and promote recycling.
It is less a subsidy program and more a regulatory framework that compels industry behavior. The three economies are thus pursuing parallel goals — more recycling, more clean-tech investment — but through fundamentally different instruments. The practical effect, across all three jurisdictions, is that capital is now being directed into recycling infrastructure and clean technology on a global scale.
The IRA’s tax credits are drawing manufacturing capacity to the United States; the EU’s binding targets are forcing waste-management upgrades; Japan’s mandate is reshaping how plastics are designed and disposed of. Each system has its own logic, but the direction of travel is the same.
What to watch next is whether the U.S. approach — heavy on tax incentives, light on mandates — can generate the same volume of recycling infrastructure that the EU’s regulatory push is demanding. The IRA’s 30% credit is generous, but it is a one-time incentive on the front end. The EU’s targets are recurring obligations that compound over time.
On closer reading, that difference in structure may prove decisive for where the next generation of recycling plants gets built.
Sources
{“@context”: “https://schema.org”, “@type”: “NewsArticle”, “headline”: “Policy Drivers: Inflation Reduction Act and EU Circular Plan”, “description”: “WASHINGTON — The Inflation Reduction Act’s climate and energy package is now in effect, and the mechanics of its tax-credit architecture are coming into sharper…”, “datePublished”: “2026-07-14T09:30:00+00:00”, “author”: {“@type”: “Person”, “name”: “Beatrice Ferrari”}, “publisher”: {“@type”: “Organization”, “name”: “InfoPulse Today”, “url”: “https://newsfeed.infopulsetoday.com/”}, “citation”: [{“@type”: “CreativeWork”, “url”: “https://en.wikipedia.org/wiki/Inflation_Reduction_Act”}]}




