
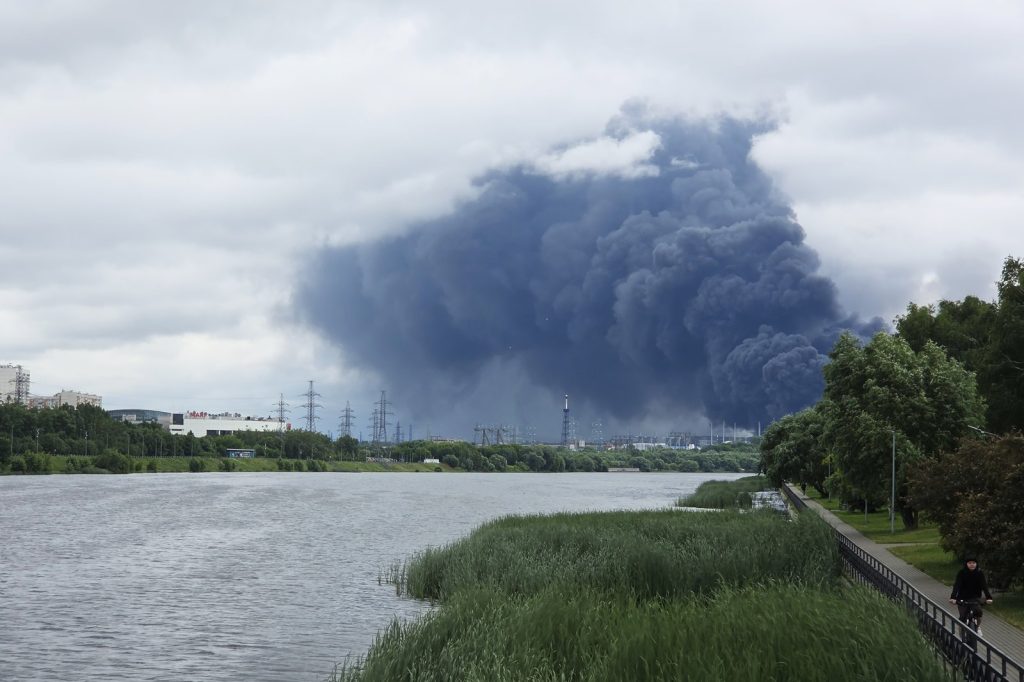
MOSCOW, July 7 — Against this backdrop of sustained conflict and shifting global energy currents, Russia’s vast oil sector finds itself under a new kind of pressure, one that originates not on the front lines of the battlefield, but in the skies above its own industrial heartland. Russia remains one of the world’s largest oil producers. In 2023, according to data from the International Energy Agency, the country was pumping roughly 10.5 million barrels of crude oil per day, exporting about 5 million barrels daily.
These revenues are not incidental to the state’s finances; oil and gas receipts constituted approximately 30 percent of Russia’s federal budget in that same year. Yet the machinery of that engine is showing signs of strain.
A series of drone strikes on Russian refineries has begun to bite into the country’s ability to process its own crude. One of the most notable attacks came on August 26, 2024, when the Omsk refinery was hit. Such strikes, the IEA has noted, can disrupt domestic refining capacity, with knock-on effects for the export of refined products like diesel and gasoline.
In 2023, Russia exported about 1.5 million barrels per day of these refined products. The attacks on refineries have contributed to a tangible rise in global diesel prices, which climbed by 10 percent in the first half of 2024, according to the IEA.
Russia has not been passive in the face of these disruptions. Moscow has been able to partially mitigate the impact of the strikes by redirecting crude oil exports to countries like China and India, both of which have increased their purchases of Russian crude since 2022. The wider picture, however, is one of diminished capacity.
The long-term effect on Russian export revenues remains uncertain, but the IEA has offered an estimate: reduced refining capacity could lower Russia’s export earnings by somewhere between $5 billion and $10 billion in 2024 alone. The Omsk refinery attack, while only one incident, illustrates a pattern. Each strike on a refinery not only reduces Russia’s capacity to produce diesel and gasoline, but also diminishes the volume of refined products it can sell on global markets.
The 10 percent rise in global diesel prices in the first half of 2024 is a direct consequence of this tightening supply. The coming months will reveal whether Russia can adapt its refining infrastructure to withstand further attacks, or whether the cumulative effect of these strikes will accelerate the decline in export revenues.
The IEA’s projection of a $5-10 billion hit to earnings in 2024 is a baseline estimate; the actual figure could move higher if the frequency or effectiveness of drone strikes increases. For now, the calculus in Moscow remains complex. The country’s ability to redirect crude exports to China and India has provided a buffer, but it cannot fully compensate for the loss of higher-value refined product sales.
Against this backdrop, the drone strikes on refineries represent a persistent, low-cost tactic that imposes real costs on the Russian state.




