Weir Group shares dropped 7 percent after the Scottish mining equipment maker disclosed that several large Minerals projects had slipped into the fourth quarter, pushing roughly £30 million of orders past the September close. Investors focused on execution risk rather than the 8 percent rise in third-quarter orders, sending the stock to around 2,440p despite management keeping full-year margin guidance above 20 percent.
Equipment Maker With A Century Of Mine Site Presence
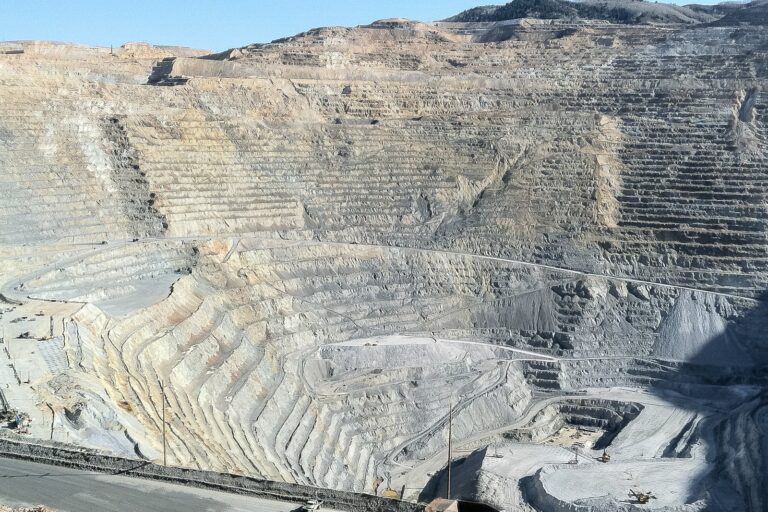
Founded in 1871 by brothers George and James Weir in Glasgow, the company built its reputation on pumping equipment for Clyde shipyards before expanding into munitions, aircraft engines and, eventually, the slurry pumps, crushers and wear parts that keep modern concentrators running. Listed in London since 1946 and now a FTSE 100 constituent, Weir operates through Minerals and ESCO divisions that service copper, gold, iron ore and oil sands operations across Chile, North America, Australia and Central Asia.
How Order Delays Cascade Into Project Timelines
When a concentrator awaits a critical pump or crusher liner, the entire comminution circuit idles. Weir’s third-quarter update noted that two delayed Minerals projects worth £30 million are now expected by year-end, a timeline that assumes freight reliability and no further geopolitical disruption. The company said customers in Chile are seeking to recover lost production after extreme weather shut mines, while phosphate demand has weakened as Middle East conflict idles roughly 90 percent of large dredging barges.
Order Growth Masked By Phasing And Weather
Group orders rose 8 percent including acquisitions, with aftermarket up 10 percent on stronger gold, copper and oil sands activity. Minerals aftermarket orders grew 7 percent, ESCO aftermarket 14 percent, and the book-to-bill ratio reached 1.10. Yet original equipment orders at ESCO fell 24 percent as large bucket and truck body orders phased after a strong first half, and organic Minerals original equipment grew only 6 percent. The company said net debt will finish slightly above its normal 0.5 to 1.5 times EBITDA range.
Copper And Lithium Supply Chains Feel The Pinch
Chile accounts for Weir’s largest copper exposure, and the weather-related shutdowns there directly throttle the feedstock that smelters in Asia and Europe rely on. Lithium brine and hard-rock projects, many of which use similar slurry and wear technology, face the same fourth-quarter conversion risk. The company said it does not expect a phosphate recovery in the quarter but also no further deterioration, while oil sands demand remains supported by higher crude prices.
Fourth Quarter Conversion Is The Test
Management targets around £870 million of revenue for the year, relying on conversion of a sizeable order backlog. Brokers at Jefferies said third-quarter intake was “unlikely to be good enough” to excite investors, while Peel Hunt and Panmure Liberum kept buy ratings arguing delayed orders should land in the fourth quarter. The SAP S/4HANA global business transformation is flagged as a margin headwind in 2027 and 2028. Two delayed Minerals projects totaling £30 million are expected by year-end.
Sources
- Weir plc
- Weir falls 7% as brokers question strength of third-quarter orders
- Weir slides despite backing guidance as investors fret over Q4 delivery
- REG – Weir PLC – Director/PDMR Shareholding
- The Weir Group Q3 Earnings Call Highlights
- Weir maintains 2026 guidance as mining demand lifts third-quarter orders by 8%
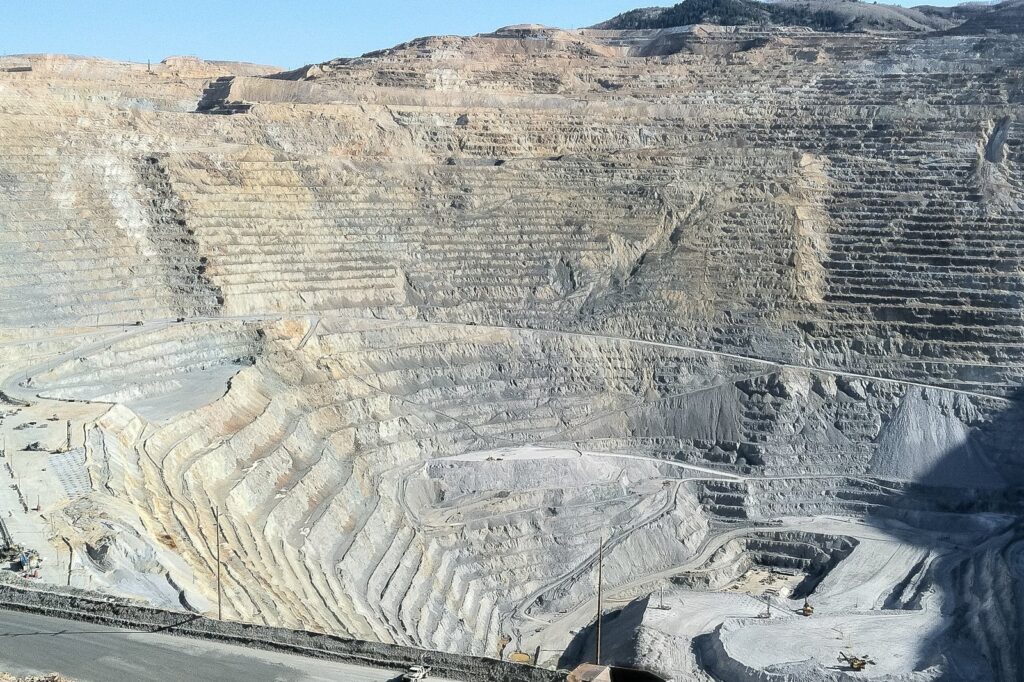
Photo: David Ratledge (CC BY 4.0)