
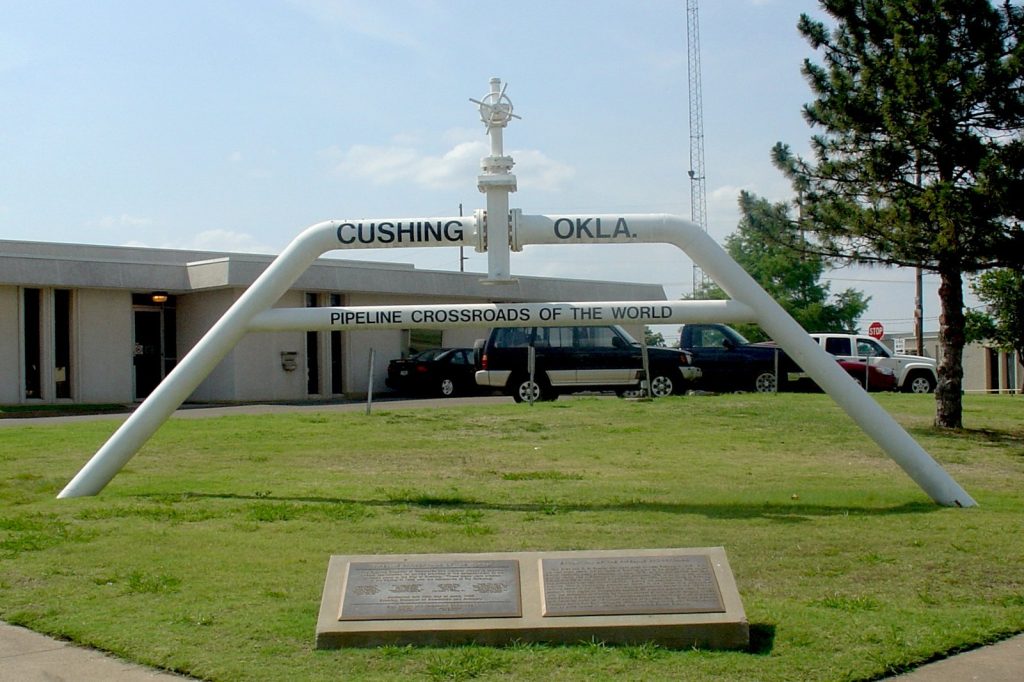
CUSHING, July 20 — West Texas Intermediate crude oil remains the dominant U.S. benchmark for global petroleum pricing, a status forged through decades of market deregulation, pipeline realignments, and the interplay between physical spot transactions and futures contracts traded on the New York Mercantile Exchange. Unlike Brent crude from the North Sea, WTI is not tied to a specific oil field. The grade, described as light sweet for its low density and low sulfur content, can be produced from any location as long as it meets the required specifications.
Strategically, the benchmark’s flexibility has allowed it to absorb production shifts across the American energy landscape.
Origins in Deregulation and Collapse
The physical spot market for WTI began on January 28, 1981, when the U.S. government decontrolled oil prices. Before that, under the Emergency Petroleum Allocation Act of 1973, WTI traded under price controls. The calculus changed dramatically with the oil price collapses of 1985–1986, which reduced local production around Cushing, Oklahoma, and linked Gulf Coast imported crude supplies into the WTI pricing mechanism.
That volatility accelerated the development of WTI futures contracts. As producers and refiners worldwide adopted the contracts, assessed physical spot prices — compiled by Price Reporting Agencies such as Platts and Argus Media starting in 1981 — became de facto benchmark prices for crude.
Eligible spot transactions at Cushing are typically reported as WTI; those at Midland, Texas, and Houston, Texas, are also included in the broader WTI assessment.
Delivery Points and Benchmark Competition
WTI crude oil is traded and delivered at Cushing, Oklahoma, a hub that historically defined the grade as local oilfield production moved between wells and refineries. As local output declined, pipelines delivered other grades that met the lightness and sweetness criteria, and the futures contract formalized that deliverable assets could be a blend of acceptable quality. Similar definitions exist for WTI Midland (delivered in Midland, Texas) and WTI Houston (at the Magellan East Houston terminal).
What this signals in the broader global market is that WTI competes with other benchmarks — Brent, Dubai crude, Oman crude, Urals oil, and the OPEC reference basket — for influence over pricing. Because WTI is lighter and sweeter than Brent and considerably lighter and sweeter than Middle Eastern grades, it often commands a premium when supply dynamics tighten.
What to Watch Next
With physical trading centered on Cushing but expanding to Houston and Midland, the geography of WTI pricing is shifting. The growth of the spot market has been propelled by the growth of the futures market, and the assessments produced by Platts and Argus Media will continue to reflect whether Gulf Coast volumes increasingly set the tone. For analysts tracking the interplay between American energy output and global crude benchmarks, the evolution of WTI delivery points is the next move on the chessboard.




