
MOSCOW, July 13 — Against the backdrop of continued Western sanctions and shifting global energy alliances, Russia’s petroleum industry has demonstrated a remarkable, if costly, resilience. The sector exported crude oil and petroleum products worth $190 billion in 2023, according to the International Energy Agency. Yet beneath that headline figure lies a story of logistical strain, redirected trade flows, and the persistent vulnerability of domestic infrastructure to attack.
The numbers are stark. Russia produces roughly 10.5 million barrels of oil per day, of which approximately 5 million barrels are exported.
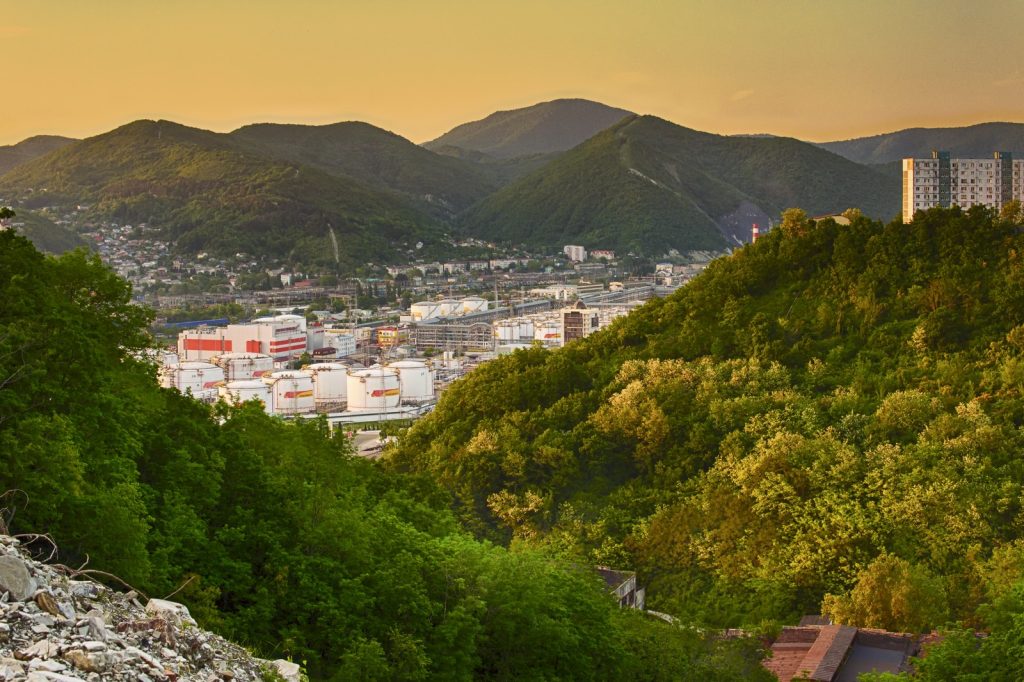
Attacks on oil depots and refineries — such as the strike in Stavropol Krai — have the capacity to temporarily reduce refining capacity and disrupt the intricate logistics that move crude from wellhead to world market. The impact is not merely theoretical.
The Tuapse Precedent
Consider the case of the Tuapse refinery on the Black Sea. In January 2024, a strike halted operations at the facility for several weeks, cutting output by 100,000 barrels per day. That single disruption, while not catastrophic in isolation, illustrates the cumulative pressure on Russia’s downstream infrastructure.
Each such event forces Moscow to recalibrate its export strategy, diverting cargoes and absorbing higher costs. The attacks have increased insurance and shipping costs for Russian crude.
These costs, while difficult to quantify precisely, erode the effective revenue per barrel that reaches Moscow.
The Pivot East
Yet Russia has not been left without options. The wider picture is one of a dramatic reorientation of trade. By 2024, China and India were buying over 80% of Russia’s seaborne crude, a stark illustration of how the global oil map has been redrawn since the invasion of Ukraine.
Moscow has redirected exports to alternative routes and customers with a speed that surprised many analysts. For the global oil market, the consequences have been contained.
Brent crude averaged $85 per barrel in 2024, a price that reflects a delicate equilibrium between supply disruptions, OPEC+ discipline, and slowing demand in parts of the developed world. The attacks on Russian infrastructure, while headline-grabbing, have not fundamentally altered this balance. Against this backdrop, the resilience of Russia’s petroleum industry remains a central fact of the global energy landscape.
The infrastructure is battered but functional. The customers have changed but remain eager.
The costs have risen but the revenue still flows. What to watch next is whether the cumulative effect of logistics disruptions and rising insurance premiums will begin to bite harder, or whether Moscow can continue to absorb these frictions as the price of doing business in a war economy. The answer will shape not only Russia’s fiscal health but the contours of the international oil trade for years to come.




