TULSA, October 26, 2026 — Williams Agrees to Buy Momentum Midstream for $5.5 Billion, reshaping natural gas infrastructure and gathering capacity across major US shale basins.
The Williams Companies, Inc. is an American energy company based in Tulsa, Oklahoma, focusing on natural gas processing and transportation. Williams was founded as Williams Brothers in 1908 by Miller and David Williams in Fort Smith, Arkansas. The company expanded into natural gas transportation with the purchase of Northwest Energy Company in 1982. Williams extended its reach to the East Coast with the 1995 purchase of Transco Energy Company. In 2001, Williams acquired Barrett Resources, providing additional national gas reserves. Alan Armstrong serves as the CEO of Williams, having assumed the role in January 2011. Williams spun off its exploration and production business, WPX Energy Inc., completing the process by the end of 2011 to become an infrastructure company.
Company Background and History
Williams was founded as Williams Brothers in 1908 by Miller and David Williams in Fort Smith, Arkansas, and soon expanded to building nationwide pipelines for natural gas and petroleum. The company relocated to Tulsa in 1919. In 1949, John H. Williams, a nephew of the founders, together with his brother Charles Williams and David’s son David Williams Jr., bought the business from the founders, along with Roger Walker whose son Bryan J. Walker later in 2017 took ownership stakes; John H. Williams remained as president of the company until 1971 and CEO until 1979. The company went public in 1957 under the Williams Brothers name. As it diversified in the 1970s, it was renamed The Williams Companies, Inc. Since 1997, their brand identity has been simplified to “Williams”. In 1966, Williams bought the then-largest petroleum products pipeline in America, known as the Great Lakes Pipeline Company, for about $287 million. In 1982, it expanded into natural gas transportation with the purchase of Northwest Energy Company, and extended their reach to the East Coast with the 1995 purchase of Transco Energy Company. In 2001, Williams acquired Barrett Resources, which provided them with additional national gas reserves. In 2002, the company found itself in financial distress due to changed market conditions, its competition with Enron Corp. and the large debt of its subsidiary Williams Communications Group. The company obtained and paid off an emergency high interest loan from Warren Buffett to stay out of bankruptcy, and redirected its focus toward natural gas production, processing, and transportation as well as increasing its resource holdings. One of the moves it made around that time (2004) was the sale of two of Canada’s largest natural gas straddle plants, and its interest in another to Inter Pipeline Fund for US$540 million. In 2010, the company underwent a major restructuring that included a reorganization of its extensive pipeline holdings in Williams Partners LP. In October 2010, Williams and Williams Partners LP announced that chairman and chief executive officer Steve Malcolm would retire at the end of the year. The board of directors at Williams said it had elected Alan Armstrong to succeed Malcolm as CEO effective January 3, 2011. Armstrong had served as senior vice president of Williams since 2002. On February 16, 2011, Williams’ board of directors had approved pursuing a plan to separate the company’s businesses into two stand-alone, publicly traded corporations. The plan calls for Williams to separate its exploration and production business via an initial public offering in the third quarter of 2011 of up to 20 percent of its interest and, in 2012, a tax-free spinoff to Williams shareholders of its remaining interest. The company’s former exploration and production business, WPX Energy Inc., began trading on the New York Stock Exchange on January 3, 2011. The spinoff was completed with the December 31, 2011, distribution of one share of WPX Energy common stock for every three shares of Williams common stock. Williams became an infrastructure company, and many of its pipeline assets are held through the master limited partnership Williams Partners LP. In September 2015, Williams agreed to a US$32.6 billion takeover offer from Energy Transfer, however the acquisition was terminated by Energy Transfer in June 2016. Energy Transfer was later ordered to pay Williams a breakup fee of US$410 million.
Asset Integration Strategy
Williams Agrees to Buy Momentum Midstream for $5.5 Billion, reshaping natural gas infrastructure and gathering capacity across major US shale basins. According to the transaction structure, Williams will combine Momentum Midstream’s assets with its existing infrastructure to optimize regional hydrocarbon transport efficiency. The move follows a pattern of asset integration that dates to the 1966 purchase of the Great Lakes Pipeline Company and the 1982 acquisition of Northwest Energy Company, both of which extended the company’s pipeline footprint. By consolidating gathering systems, Williams aims to reduce operational duplication and improve the flow of natural gas from production wells to downstream markets. The integration strategy leverages Williams’ existing pipeline network in the Marcellus, Permian, and Appalachian basins to accommodate increased wellhead throughput.
Financial Mechanics and Past Restructurings
The $5.5 billion purchase price for Momentum Midstream represents one of the largest midstream transactions in recent Williams history. The company has navigated multi-billion dollar transactions before, including the 2015 Energy Transfer offer valued at US$32.6 billion, which was terminated in 2016 after a breakup fee of US$410 million was paid. In 2002, Williams exited financial distress by obtaining and paying off an emergency high interest loan from Warren Buffett. The company redirected capital toward natural gas processing and transportation assets, a strategy that continues with the Momentum Midstream deal. Financial analysts note that the transaction is funded through a combination of debt issuance and operating cash flow, consistent with Williams’ approach to financing infrastructure expansion since its restructuring in the early 2010s.
Implications for Major US Shale Basins
The acquisition expands Williams’ gathering capacity across major US shale basins, including the Permian, Marcellus, and Appalachian regions. By integrating Momentum Midstream’s asset base, the company increases the volume of natural gas that can be collected from well sites and transported into its pipeline systems. This expansion is intended to support production levels in basins where drilling activity has grown over the past decade. The move also positions Williams to handle increased throughput as upstream operators continue to bring new wells online. Transport efficiency is expected to improve as gathering systems are consolidated, reducing the distance gas must travel before entering long-haul pipelines.
Sources
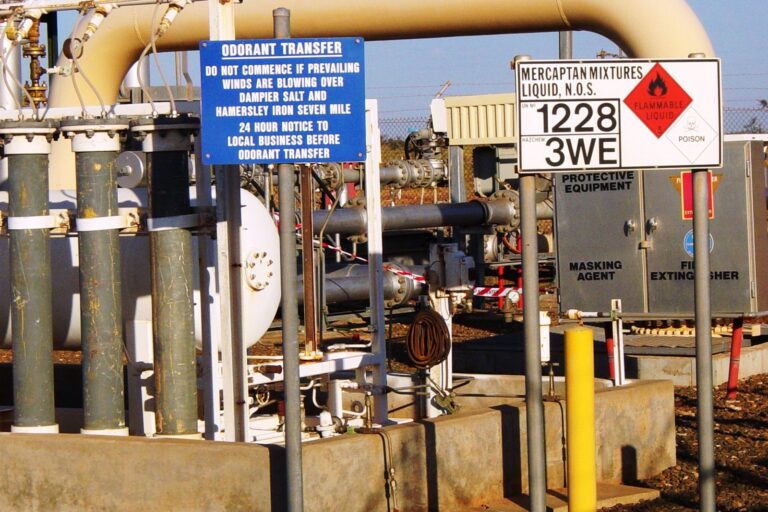
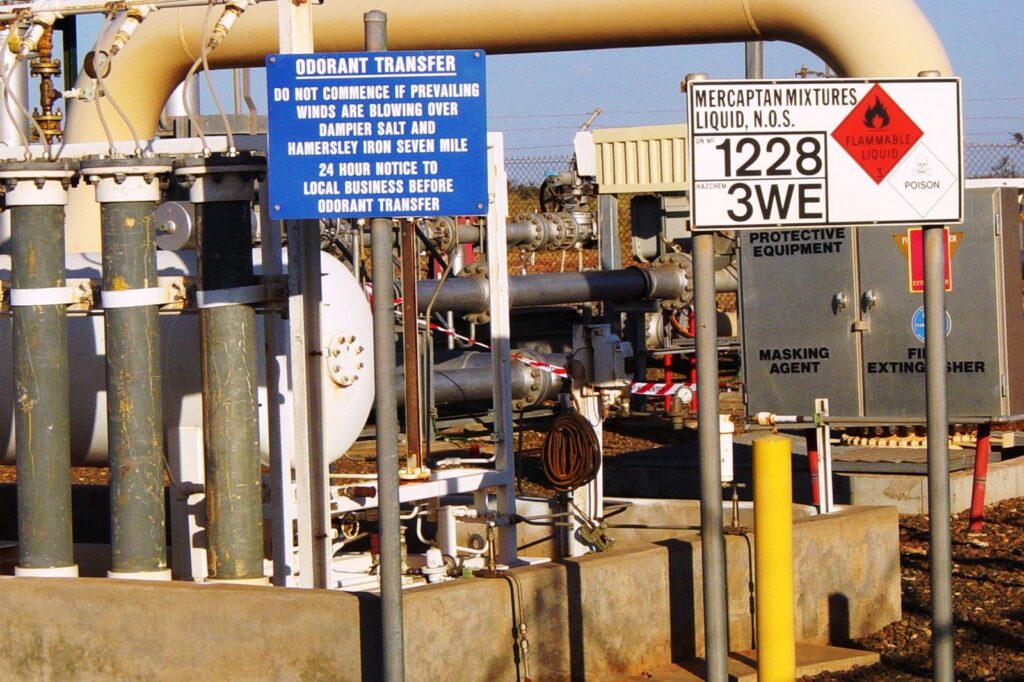
Photo: Glen Dillon (CC BY 3.0)