
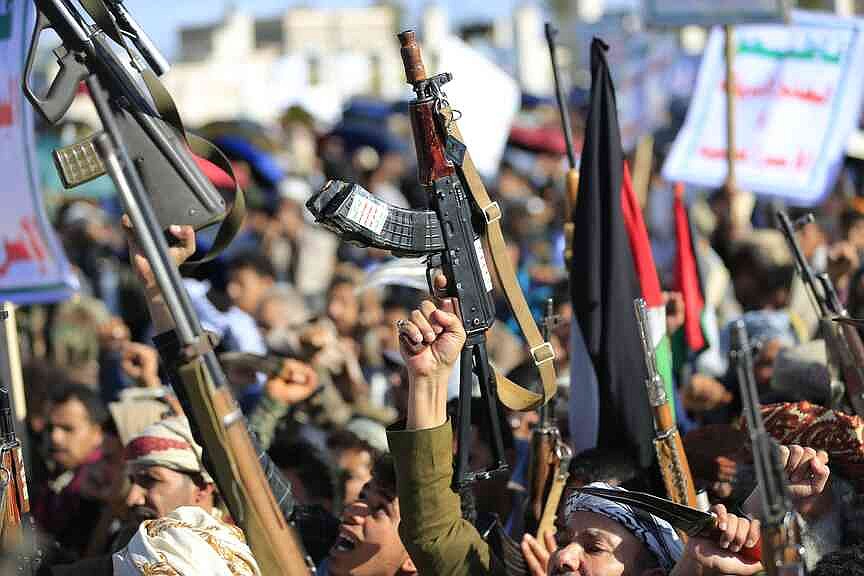
WASHINGTON, July 20 — As geopolitical tensions in the Middle East simmer, the global oil market is once again confronting the risk of severe disruption. Oil prices, which have already swung violently over the past few years, are acutely sensitive to any escalation involving Iran, the Houthi movement, or the critical chokepoints of the Persian Gulf. Think of the global oil market as a giant plumbing system — any blockage sends pressure rippling outward.
And right now, several valves are under strain. The benchmark Brent crude price rose from $70 per barrel in October 2023 to over $90 in January 2024 after Houthi Red Sea attacks and U.S. airstrikes.
That spike followed the earlier shock of Russia’s 2022 invasion of Ukraine, which pushed Brent above $120 per barrel. Iran, a major OPEC member with production capacity of about 3.8 million barrels per day, has been under U.S. sanctions since 2018. Those restrictions have limited its exports to roughly 1.5–2 million barrels per day, largely via smuggling.
A direct U.S.–Iran conflict could shut down those flows entirely. The Houthi threat is equally consequential.
A blockade of Saudi Red Sea ports would threaten Saudi exports of 9 million barrels per day through the Bab el-Mandeb, the narrow strait connecting the Red Sea to the Gulf of Aden. The alternative shipping route around the Cape of Good Hope adds 10–14 days of travel time and significantly higher costs. The U.S. Energy Information Administration has estimated that a disruption to the Bab el-Mandeb could affect 6.2 million barrels per day of oil flows.
What’s at Stake
Past oil shocks offer a grim reference. The 1973 Arab oil embargo, the 1979 Iranian Revolution, the 1990 Iraqi invasion of Kuwait, and the 2003 Iraq War all triggered price spikes that reverberated through the global economy. Oil prices directly impact inflation and central bank policy.
The Federal Reserve raised interest rates 11 times from March 2022 to July 2023 to combat inflation, which peaked at 9.1% in June 2022. Any new supply shock would complicate the Fed’s task.
The U.S. Strategic Petroleum Reserve, a key emergency buffer, held 371 million barrels as of March 2024 — down from 638 million in 2020. The United States has released about 300 million barrels from the SPR since 2022 to stabilize prices. That drawdown has left the reserve at its lowest level in decades, limiting the government’s ability to respond to a fresh crisis.
The practical upshot for ordinary readers: any escalation that cuts off Iranian exports or blocks Saudi shipments through the Bab el-Mandeb could quickly translate into higher prices at the refinery gate, and eventually into what we pay for gasoline and heating oil. With the SPR diminished and the Fed still watching inflation closely, the room for error is shrinking.




