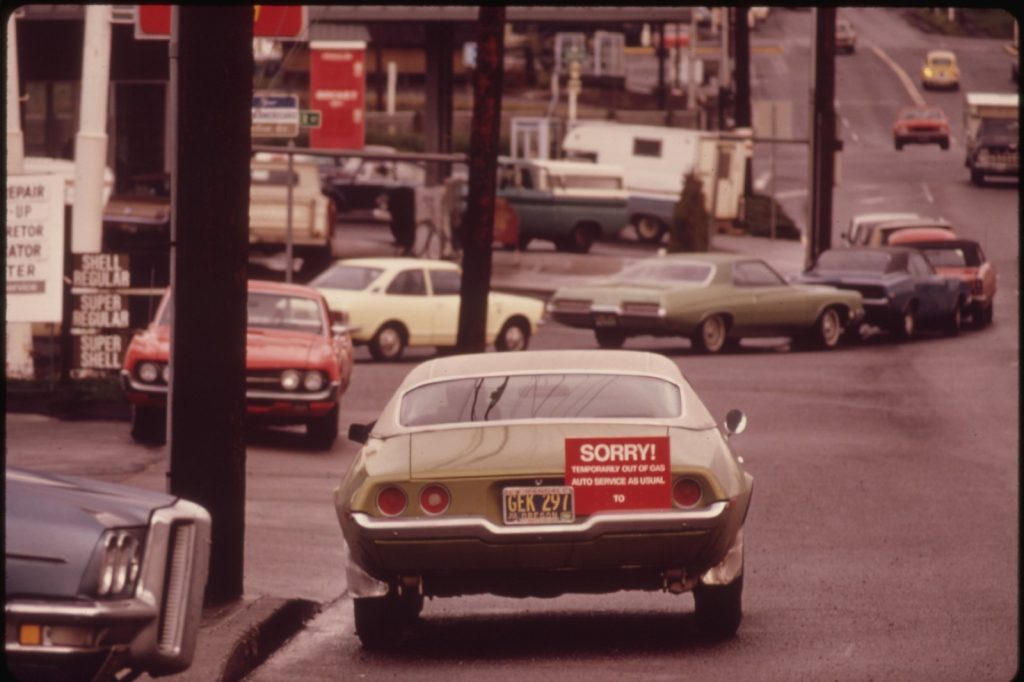
WASHINGTON, D.C., August 1 — History records a clear precedent for how significant disruptions to global oil supply can initiate widespread economic instability. The 1973 oil crisis serves as a foundational example, beginning in October of that year with a decisive action by Arab members of the Organization of Arab Petroleum Exporting Countries (OAPEC). According to the historical record, OAPEC members imposed an oil embargo against nations perceived as allies of Israel during the Yom Kippur War.
This move had an immediate and dramatic effect on global crude oil prices. Prices, which stood at around $3 per barrel in early 1973, quadrupled to nearly $12 per barrel by March 1974.
The Precedent of Supply Shocks
The sudden escalation in energy costs triggered widespread economic instability, characterized by significant inflation and a reduction in economic growth, a condition subsequently termed stagflation. The U.S. economy, on the timeline, entered a recession that spanned from November 1973 to March 1975. During this period, the nation’s Gross Domestic Product contracted by 3.2% in the first quarter of 1974 alone.
Unemployment figures also reflected the downturn, rising from 4.6% to 9.0% over the course of the crisis. A second major oil shock followed in 1979.
This disruption was precipitated by the Iranian Revolution, with further regional destabilization occurring after the outbreak of the Iran-Iraq War in 1980. Iran, a significant global oil producer, saw its production fall drastically. Global oil prices doubled in response, escalating from approximately $14 per barrel to $35 per barrel by 1981.
Lessons from Instability
This second shock contributed to a severe global recession in the early 1980s. The U.S. experienced two distinct recessions between January 1980 and November 1982. The Federal Reserve, under Chairman Paul Volcker, responded to the inflationary pressures by aggressively raising interest rates.
The federal funds rate reached a peak of 20% in June 1981, a measure that further tightened credit and slowed economic activity across the country. These historical events collectively demonstrate a clear causal link: geopolitical instability in major oil-producing regions leads directly to supply shocks.
These shocks, in turn, drive up energy costs, fuel inflation, reduce both consumer and business spending, and ultimately contribute to economic contractions. The record shows a consistent pattern. As the global economy continues to grapple with post-pandemic recovery and existing geopolitical tensions, it remains particularly vulnerable to such a shock.
Institutions like the World Bank have issued warnings of a potential ‘lost decade’ of growth should major disruptions occur, underscoring the enduring relevance of these historical precedents.