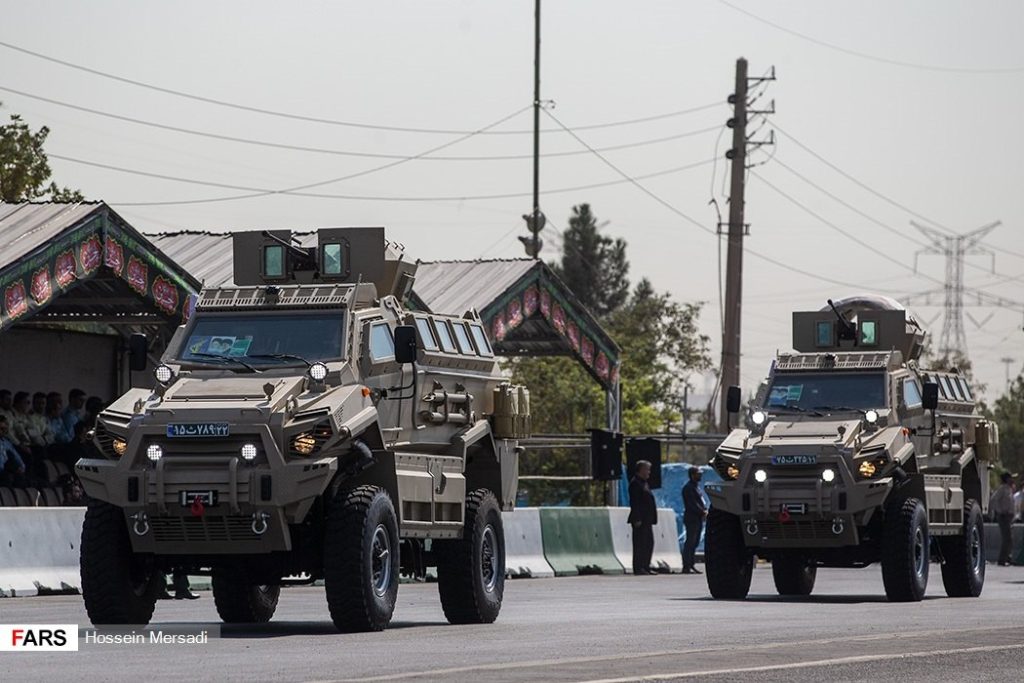
LONDON, July 12 — Oil markets have been on edge since late April, when Iran’s Islamic Revolutionary Guard Corps announced the closure of the Strait of Hormuz, a chokepoint through which roughly 20% of the world’s daily oil consumption passes. The strait handles about 21 million barrels per day, according to the U.S. Energy Information Administration. Brent crude jumped more than 5% on the news, pushing above $90 a barrel.
For all the noise in the weeks since, the salient point remains the sheer volume of supply at risk.
A chokepoint with history
This is not the first time the strait has rattled markets. The last significant price spike tied to the waterway came in September 2019, when attacks on Saudi Aramco facilities temporarily cut 5.7 million barrels per day of production. That event caused a 15% price jump.
The current disruption, however, is different in kind. It is a deliberate state-directed closure, not a one-off strike.
Analysts now warn that a prolonged blockage could push oil above $100 a barrel, with consequences for global inflation and economic growth that would be felt well beyond the trading floors.
Who gets hit
The major importers most exposed are China, Japan, India and South Korea, all of which rely on Persian Gulf oil. For these economies, the closure represents a direct supply risk that no amount of spot-market buying can fully hedge. Alternative pipelines exist, but they are not enough.
Saudi Arabia’s East-West Pipeline can move up to 5 million barrels per day, bypassing the strait to the Red Sea. The UAE’s Habshan-Fujairah pipeline adds another 1.5 million barrels per day of capacity.
Together, they replace less than a third of the volume that normally transits Hormuz. The disruption is not limited to oil. Qatar, the world’s largest LNG exporter, shipped 106 billion cubic meters of liquefied natural gas in 2023, most of it through the strait.
That flow is now threatened as well.
Markets react
Global stock markets fell in Asia and Europe following the IRGC’s announcement. S&P 500 futures dropped 1.5%, a signal that investors were pricing in a broader economic drag. The question now is how long the closure lasts, and whether diplomatic channels — or military ones — can reopen the waterway before the price effects compound.
For all the noise, the facts on the ground remain unchanged: roughly a fifth of the world’s oil supply moves through a single narrow channel, and that channel is shut.